
Blockchain technology is changing how digital information can be recorded, verified, and shared across computer networks. Originally developed as the foundation for Bitcoin, blockchain has attracted interest from industries such as finance, healthcare, supply chain management, and digital identity. Its ability to maintain a shared, tamper-resistant record makes it an important development in modern information technology.
Unlike traditional databases, which are often managed by a central organization, many blockchain networks distribute records among multiple participants. Transactions are grouped into blocks and connected using cryptographic techniques. This structure makes unauthorized changes difficult, particularly on established networks where numerous participants independently verify the same transaction history.
Understanding what blockchain technology is and how it works does not require advanced programming knowledge. This guide explains blockchain in simple terms, including blocks, cryptography, decentralization, consensus mechanisms, and smart contracts. It also explores practical applications, advantages, limitations, and the future of blockchain technology.
What Is Blockchain Technology?
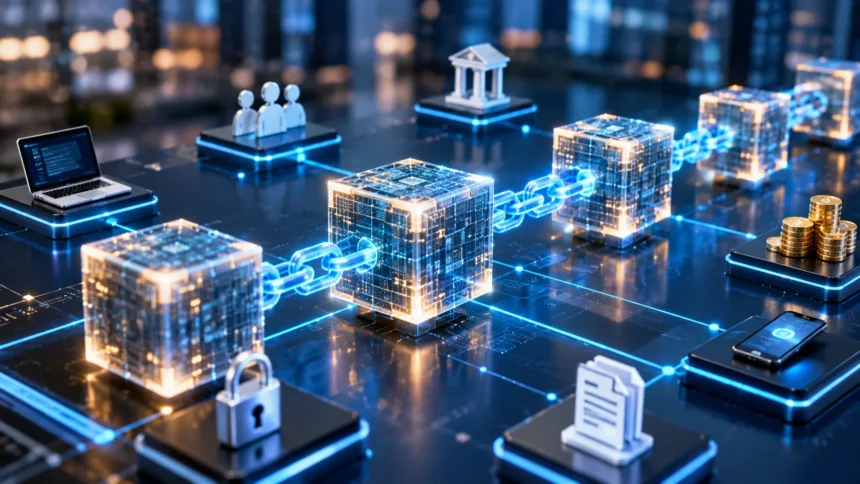
Blockchain technology is a type of distributed digital ledger that records information in a sequence of connected blocks. Each block contains transaction data, a reference to the previous block, and other information required by the network. These connections help create a chronological record that participants can independently examine and verify.
Many blockchain networks maintain copies of their ledgers across multiple computers, commonly called nodes. Instead of relying on one organization to update the entire record, participants follow agreed rules for validating changes. The precise level of decentralization depends on how the blockchain is designed and who has permission to participate.
Blockchain is widely associated with cryptocurrencies, but its underlying principles can support other applications. Organizations have explored distributed ledgers for tracking goods, recording digital ownership, and coordinating information between parties. Whether blockchain is appropriate depends on the problem being addressed and the alternatives available.
How Does Blockchain Technology Work?
Blockchain technology works by organizing verified transactions into blocks that become part of a shared digital ledger. When someone submits a transaction, the network checks whether it satisfies relevant rules. Depending on the blockchain, these checks may involve digital signatures, available balances, permissions, or other conditions established by its protocol.
Valid transactions are gathered into proposed blocks. A consensus mechanism determines how the network agrees on which blocks should be added to the ledger. Once accepted, each new block references an earlier block, creating a linked sequence of recorded information.
The resulting chain can be examined by network participants according to its access rules. Changing older records would typically require overcoming the network’s cryptographic and consensus protections. However, blockchain security is not absolute, and the difficulty of reversing transactions varies across different network designs.
Understanding the Structure of a Blockchain
A blockchain consists of individual blocks connected through cryptographic references. Each block usually contains a collection of transactions and information describing its relationship to the existing ledger. The exact structure varies depending on the software, consensus mechanism, and purpose of the network.
A typical block header may contain a timestamp, reference to the previous block, and a cryptographic summary of transaction information. Some networks also include values used during the consensus process. These components allow participants to examine whether the proposed block follows the network’s established rules.
Connecting blocks through cryptographic hashes makes modifications easier to detect. If information in an earlier block changes, the associated hash usually changes as well. This disrupts the expected relationship between blocks, allowing properly functioning network participants to identify inconsistencies in the ledger.
What Are Blocks in Blockchain Technology?
A block is a structured collection of information added to a blockchain ledger. In cryptocurrency networks, blocks commonly contain records of transactions involving digital assets. Other blockchain applications may store references to documents, ownership information, or events relevant to a particular system.
Blocks usually have limits on the amount of information they can contain. Those limits may involve total data size, transaction capacity, or computational resources needed to process their contents. Different blockchain networks use different approaches to managing these constraints.
After a block has been accepted through the relevant consensus process, it becomes part of the recorded transaction history. New blocks extend that history by referencing previous records. The strength of this structure comes from the combination of cryptographic links, validation rules, and network participation.
What Is Decentralization in Blockchain?
Decentralization refers to distributing certain responsibilities across multiple participants rather than placing all control in one authority. In blockchain networks, these responsibilities may include maintaining records, validating transactions, and participating in consensus. The degree of decentralization varies significantly between systems.
Public networks such as Bitcoin allow independent participants to operate software and verify ledger information. Permissioned blockchains, by comparison, may restrict participation to approved organizations. Both approaches use distributed ledger concepts, but they offer different levels of openness, governance, and administrative control.
Decentralization can reduce dependence on a single operator, but it also introduces coordination challenges. Network participants need common rules for handling transactions, upgrades, and disagreements. Effective governance is therefore important, even when no single organization directly manages every aspect of the network.
What Is a Distributed Ledger?
A distributed ledger is a database whose records are shared or synchronized across multiple participants. Each authorized participant may maintain a copy of the information or access a common verified history. This arrangement differs from conventional systems where one organization maintains the primary authoritative database.
Blockchain is one form of distributed ledger technology, commonly abbreviated as DLT. Its distinguishing feature is the use of cryptographically connected blocks to organize records. However, not every distributed ledger uses a blockchain structure, and some systems employ different methods of organizing and validating information.
Distributed ledgers can help organizations coordinate records when several parties need access to consistent information. Their usefulness depends on trust relationships, performance requirements, and the need for shared verification. A conventional database may still be simpler and more efficient when one trusted organization can manage the information.
How Cryptography Makes Blockchain Secure
Cryptography plays a central role in protecting blockchain information and verifying transactions. Many networks use digital signatures to confirm that a transaction was authorized by someone controlling the relevant private key. These mathematical techniques help participants validate transactions without revealing the private key itself.
Cryptographic hashing is another important component. A hash function converts input data into a fixed-length output that changes unpredictably when the input changes. Blockchain systems use hashes to connect blocks, summarize transaction information, and detect attempts to modify recorded data.
Although cryptography provides strong protections, it does not eliminate every security risk. Software vulnerabilities, stolen private keys, compromised devices, and poorly designed applications can still cause problems. Blockchain security depends on correct implementation, responsible key management, and the design of the wider system.
What Is Blockchain Consensus?
Consensus is the process through which blockchain participants agree on the valid state of a shared ledger. Without a mechanism for reaching agreement, different computers could accept conflicting transaction histories. Consensus rules help networks decide which proposed blocks belong in the accepted record.
Different blockchain networks use different consensus mechanisms. Two well-known approaches are Proof of Work and Proof of Stake. Each establishes procedures for proposing and validating blocks, while also creating different security assumptions, resource requirements, and participation incentives.
Consensus is especially important in public blockchains where participants may not know or trust one another. The system must discourage dishonest behavior and maintain consistency despite network delays or competing proposals. No consensus mechanism is perfect, so its benefits and limitations should be evaluated carefully.
Proof of Work vs Proof of Stake
Proof of Work is a consensus approach in which participants, often called miners, perform computational work to compete for the opportunity to propose new blocks. Bitcoin uses this mechanism. Its security depends partly on the substantial resources required to attack the network.
Proof of Stake uses a different model in which validators commit eligible digital assets as part of their participation in consensus. The protocol determines how validators propose or attest to blocks and may penalize certain forms of dishonest behavior. Ethereum is a prominent example of a Proof of Stake blockchain.
These systems differ in energy requirements, hardware needs, incentives, and security assumptions. Proof of Stake generally avoids the extensive computational competition associated with Proof of Work. However, both approaches involve technical and governance tradeoffs, and neither guarantees complete protection against every possible attack.
What Are Public and Private Blockchains?
A public blockchain generally allows anyone to access its ledger and participate according to the network’s published rules. Bitcoin and Ethereum are familiar examples. Public networks often emphasize openness, independent verification, and participation without requiring approval from a central administrator.
Private blockchains restrict certain activities to selected participants. An organization might control who can view information, submit transactions, or validate records. These systems can be useful when businesses require shared records but must also enforce confidentiality or administrative permissions.
The distinction affects transparency, performance, governance, and trust. Public blockchains typically support wider independent participation, while private systems can offer greater control over access and operations. The appropriate design depends on whether the intended application prioritizes openness, privacy, coordination, or organizational oversight.
What Are Smart Contracts in Blockchain?
Smart contracts are programs that execute predefined rules within a compatible blockchain environment. They can manage digital assets, apply agreed conditions, or coordinate interactions between users and applications. Unlike ordinary legal contracts, smart contracts are software instructions and do not automatically create legally enforceable agreements.
For example, a smart contract may update a digital ownership record when specified conditions are satisfied. The network executes the program according to its established rules. This can reduce the need for manual processing in certain workflows, although real-world information may still require external verification.
Smart contracts can contain programming errors or insecure assumptions. Because blockchain transactions may be difficult or impossible to reverse, software vulnerabilities can have serious consequences. Careful design, testing, and independent security reviews are therefore important when developing applications that rely on smart contracts.
Blockchain Technology and Cryptocurrency
Cryptocurrency is one of the best-known applications of blockchain technology. Digital currencies such as Bitcoin use blockchain records to maintain a shared history of transactions. Network participants validate transfers according to protocol rules without depending on a conventional bank to maintain the entire ledger.
Blockchain and cryptocurrency are closely connected, but they are not identical concepts. Blockchain describes a way of organizing and verifying records, while cryptocurrency refers to a category of digital assets. Some blockchains support digital currencies, while others focus on business records or specialized applications.
Cryptocurrency markets also involve risks that are separate from the underlying ledger technology. Prices can fluctuate significantly, and digital assets may face cybersecurity, legal, and consumer protection concerns. Understanding blockchain does not require purchasing cryptocurrency or participating in speculative financial markets.
Blockchain vs Traditional Databases
Traditional databases generally allow authorized administrators to create, update, and delete records according to established permissions. They are widely used because they can process information efficiently and support complex applications. A centralized database may be the most practical solution when one trusted organization manages the system.
Blockchain databases differ because accepted records are connected through cryptographic references and maintained under shared validation rules. This architecture can provide independent verification across multiple organizations. However, it may also introduce additional computational, storage, and coordination requirements.
Choosing between blockchain and a traditional database requires understanding the intended problem. When participants need independently verifiable records without relying entirely on one administrator, blockchain may provide advantages. When trust and centralized management are already established, conventional databases can offer simpler and more efficient solutions.
Benefits of Blockchain Technology
One major benefit of blockchain technology is the ability to maintain a shared record that multiple participants can verify. This can reduce disagreements about which transactions were recorded. Cryptographic links and consensus mechanisms also make unauthorized historical modifications more difficult in appropriately secured networks.
Transparency is another potential advantage, particularly on public blockchains where transaction histories can be examined. However, visible transactions do not necessarily reveal the real-world identities of the people involved. Privacy protections and access controls depend on the specific network and application.
Blockchain may also help automate certain processes and coordinate records between organizations. Smart contracts and shared ledgers can reduce repetitive reconciliation tasks in suitable circumstances. These benefits are not universal, so businesses should compare blockchain systems with simpler technological alternatives before adopting them.
Challenges and Limitations of Blockchain
Scalability is an important challenge for many blockchain networks. Processing transactions across numerous independent participants can introduce delays and resource requirements. Some networks use additional technical layers or alternative architectures to increase capacity, but these approaches involve their own tradeoffs.
Privacy and data management also present challenges. Public ledgers may expose transaction information permanently, creating concerns when records are linked to identifiable individuals. Storing sensitive personal information directly on an immutable ledger can conflict with certain privacy and data protection requirements.
Other limitations include software complexity, governance disagreements, regulatory uncertainty, and security vulnerabilities in connected applications. Blockchain systems may also require specialized expertise to maintain. These concerns demonstrate why the technology should be evaluated according to practical requirements rather than treated as a universal replacement for existing databases.
How Blockchain Is Used in Banking and Finance
Financial institutions have explored blockchain technology for payment processing, asset settlement, and record reconciliation. Shared ledgers may help authorized organizations coordinate information without maintaining completely separate transaction histories. However, production systems must still satisfy regulatory, privacy, and operational requirements.
Tokenization is another area of financial experimentation. This involves representing certain rights or assets through digital tokens managed by a technical system. Depending on the design, blockchain may support recordkeeping and transfer processes, although legal ownership and enforceability depend on applicable laws.
Financial blockchain applications face significant challenges involving security, governance, interoperability, and compliance. Banks must also evaluate whether distributed systems provide meaningful advantages over established financial infrastructure. Successful adoption depends on demonstrated efficiency and reliability rather than technological novelty alone.
Blockchain in Supply Chain Management
Supply chain management involves coordinating information as goods move between producers, transport providers, warehouses, and retailers. Blockchain systems can provide a shared record of selected events across these organizations. This may help participants review shipment histories and reduce inconsistencies between separate business records.
For example, a distributed ledger could record when a product leaves a manufacturing facility or arrives at a distribution center. Authorized participants may then verify those updates. However, blockchain cannot independently prove that every real-world event occurred exactly as recorded.
Accurate supply chain tracking therefore depends on trustworthy data collection and effective operational controls. Sensors, inspections, and verified documentation may provide information that the ledger preserves. Blockchain can support traceability, but it cannot eliminate human error, fraudulent input, or problems in physical transportation systems.
Blockchain Technology in Healthcare
Healthcare organizations have explored blockchain for coordinating records, verifying information, and tracking certain medical supply chains. Potential applications include maintaining audit trails and recording permissions associated with data access. However, handling medical information requires particularly strong privacy and security protections.
A blockchain-based healthcare system does not necessarily store complete medical records directly on its ledger. In many proposed designs, sensitive information remains in protected databases while the blockchain records references or verification information. This approach can help reduce unnecessary exposure of personal medical details.
Healthcare applications also face challenges involving interoperability, patient consent, regulation, and data correction. Medical information must remain accurate and accessible to appropriately authorized professionals. Blockchain may support specific administrative functions, but it is not a substitute for secure clinical systems or professional healthcare judgment.
Blockchain in Digital Identity Verification
Digital identity systems help establish whether a person or organization is entitled to access particular services. Blockchain-based approaches may support verifiable credentials or shared records of certain identity-related claims. These systems aim to reduce repeated verification processes while allowing information to be checked securely.
Some identity frameworks use cryptographic credentials that individuals can present to approved verifiers. A blockchain may support associated registries or verification infrastructure without storing sensitive personal details publicly. The exact level of privacy depends on the architecture and implementation.
Digital identity remains a complex area because identity information can change or require correction. Lost credentials, compromised devices, and legal requirements must also be considered. Effective systems need strong governance and privacy protections regardless of whether blockchain is part of their design.
Blockchain in Real Estate and Property Records
Real estate transactions involve ownership records, contracts, financial institutions, and public authorities. Blockchain has been explored as a technology for coordinating some of this information. Shared records could potentially improve transparency or reduce repeated reconciliation between participating organizations.
Another proposed application involves representing certain property-related rights through digital tokens. However, a token does not automatically establish legal ownership of a physical building. Property rights remain governed by applicable laws, registration systems, and enforceable agreements.
Widespread adoption would require cooperation between technology providers, legal institutions, and property authorities. Accurate records and reliable identity verification are especially important when valuable assets are involved. Blockchain may support administrative improvements, but its usefulness depends on integration with established legal systems.
Is Blockchain Technology Safe and Secure?
Blockchain networks can provide strong security through cryptography, distributed verification, and consensus mechanisms. These features make certain forms of unauthorized modification difficult. On well-established public networks, attempting to rewrite accepted transaction history may require substantial resources.
However, blockchain does not guarantee complete safety. Problems can arise from compromised private keys, vulnerable smart contracts, faulty applications, or dishonest service providers. The security of the underlying ledger is only one part of the overall system.
Responsible blockchain implementation requires secure software development, independent review, appropriate access controls, and ongoing maintenance. Users should also understand that some transactions cannot be easily reversed. Evaluating both technical protections and operational risks is essential before trusting a blockchain-based application.
Future of Blockchain Technology
The future of blockchain technology will depend on whether it solves practical problems more effectively than existing systems. Developers continue to explore improvements involving scalability, interoperability, privacy, and transaction efficiency. These areas are important because technical limitations can prevent otherwise promising applications from becoming practical.
Regulatory developments may also influence blockchain adoption across different industries. Financial services, digital identity, and asset management applications often require clear legal responsibilities and consumer protections. Organizations must balance experimentation with obligations concerning security, transparency, and accountability.
Blockchain is likely to remain an area of technological research and business experimentation. Some applications may become widely adopted, while others may prove unnecessarily complicated or inefficient. Its long-term value will depend on measurable usefulness rather than predictions that every industry will eventually rely on distributed ledgers.
Conclusion
Blockchain technology is a distributed ledger system that records information in cryptographically connected blocks. It allows participants to maintain and verify a shared transaction history according to established network rules. Understanding concepts such as decentralization, cryptographic hashing, and consensus makes its operation easier to explain.
Although blockchain is best known for supporting cryptocurrencies, its potential applications extend into finance, supply chains, healthcare, and digital identity. These uses may offer advantages involving transparency, verification, and coordination. However, challenges involving scalability, privacy, security, and governance must also be considered.
Learning what blockchain technology is and how it works provides a valuable foundation for understanding modern digital systems. The technology offers useful possibilities, but it is not necessary or appropriate for every application. Evaluating its practical benefits and limitations is the best way to understand its role in the future of technology.
Frequently Asked Questions (FAQs)
What is blockchain technology in simple words?
Blockchain is a digital recordkeeping system that stores information in connected blocks. Multiple participants can verify the records according to shared rules, making unauthorized changes difficult in properly secured networks.
How does blockchain technology work step by step?
A blockchain receives transactions, checks them against network rules, groups valid transactions into proposed blocks, and uses consensus to establish an accepted record. Each accepted block references previous information.
What is the main purpose of blockchain technology?
Blockchain helps participants maintain a shared, verifiable record without always relying on a single central administrator. Its usefulness depends on whether an application requires distributed verification, coordination, or tamper-resistant records.
Is blockchain the same as Bitcoin?
No. Blockchain is a technology for maintaining distributed digital records, while Bitcoin is a cryptocurrency that uses blockchain. Other blockchain systems support different digital assets, applications, or organizational recordkeeping processes.
Can blockchain technology be hacked?
Blockchain systems are not completely immune to attacks. Although cryptography and consensus protect transaction histories, vulnerabilities in software, smart contracts, connected services, or private key management can still create security risks.